Storing wealth outside the banking system
In recent years, some savers have begun gradually rethinking how and where they hold their wealth.
This does not mean abandoning banks altogether. For most people, banks remain an essential and practical part of everyday financial life. However, there is growing interest in diversifying savings beyond the traditional banking system, particularly as financial infrastructure becomes increasingly digital.
This shift is typically quiet and measured. It is not driven by panic or extreme views, but by a desire for balance, control, and resilience in an evolving economic environment.
As with any financial decision, understanding the motivations behind this behaviour can provide useful context.
The Changing Role of Banks in Modern Finance
Banking has evolved significantly over the past two decades.
Today, most financial activity takes place digitally. Salaries are paid electronically, purchases are made through contactless payments, and savings are managed through online accounts or mobile apps.
This digital infrastructure has created enormous convenience. Payments are faster, transfers are easier, and financial management is more accessible than ever before.
At the same time, the shift toward a fully digital system has increased reliance on institutions, platforms, and financial intermediaries. Access to savings now depends not only on ownership, but on systems functioning as expected.
For many savers, this is simply part of modern life. For others, it raises questions about concentration risk, the idea that holding all wealth within one system may create unnecessary exposure.
What Is Driving This Behaviour?
The decision to hold some assets outside the banking system is rarely based on a single factor. Instead, it tends to reflect a combination of economic awareness and personal preference.
Several themes appear consistently.
Desire for Greater Control
Some savers value having a portion of their wealth held independently of financial institutions.
This does not necessarily reflect distrust. Rather, it reflects a preference for diversification across different forms of custody.
Just as investors diversify across asset classes, some choose to diversify across where assets are held.
Maintaining a mix of financial and tangible assets can create a broader sense of balance.
Read 'Protecting Your Wealth in an Increasingly Digital World'
Awareness of System Concentration Risk
Modern financial systems are highly interconnected. Savings accounts, pensions, investment platforms, and payment infrastructure often rely on overlapping institutional frameworks.
For some savers, this concentration highlights the importance of spreading risk.
Diversification has long been a core financial principle. Traditionally this meant spreading investments across equities, bonds, property, and commodities.
Increasingly, some investors are also considering diversification across custody structures.
Privacy Considerations
As financial systems become more digital, transaction visibility naturally increases.
Compliance frameworks, fraud prevention measures, and regulatory requirements have expanded significantly in recent years. These developments serve important functions within the financial system.
However, some individuals place value on maintaining a degree of financial privacy where possible within legal frameworks.
This does not imply secrecy or avoidance of regulation. Rather, it reflects a general preference for discretion when managing personal finances.
Macro-Economic Uncertainty
Periods of economic uncertainty often encourage savers to review how their assets are positioned.
Factors such as inflation, interest rate changes, currency fluctuations, and geopolitical events can all influence how individuals think about long-term financial resilience.
During uncertain periods, many investors prioritise stability and diversification over maximum short-term returns.
This often includes reviewing how wealth is structured, not just what assets are owned.
Read 'Gold vs Cash: Which Holds Value in a Crisis?'
CBDCs and the Future of Digital Money
Central Bank Digital Currencies (CBDCs) have become an increasingly discussed topic within financial policy.
CBDCs are digital forms of national currency issued by central banks. They are being explored by many countries as part of broader modernisation efforts in payment systems.
Potential benefits include improved transaction efficiency, reduced settlement times, and enhanced financial inclusion.
At the same time, the concept of fully digital currency has prompted discussion around financial infrastructure, privacy, and system resilience.
While CBDCs remain in development stages in many regions, their emergence reflects the continued evolution of how money functions in a digital economy.
For some savers, this reinforces the value of maintaining a diversified approach to storing wealth.
Withdrawal Limits and Liquidity Awareness
Banks play an essential role in managing liquidity across the financial system.
Operational processes such as transfer limits, withdrawal thresholds, and payment reviews are part of maintaining security and regulatory compliance.
For most customers, these safeguards function smoothly and without disruption.
However, awareness of how liquidity operates within financial institutions has encouraged some savers to consider holding a portion of assets in forms that can be accessed independently of digital networks.
This is typically part of broader financial planning rather than a reaction to any specific event.
Diversification Beyond Traditional Accounts
Diversification has traditionally referred to spreading investments across asset classes.
Equities, bonds, property, and cash have historically formed the foundation of diversified portfolios.
Increasingly, some investors are also considering how assets are held.
This may include:
- assets held within financial institutions
- assets held within pension structures
- tangible assets held directly
Each structure carries different characteristics in terms of liquidity, accessibility, and independence from financial infrastructure.
The objective is not to replace one system with another, but to avoid unnecessary concentration.
Read 'Diversifying Your Investment Portfolio with Precious Metals'
The Role of Physical Assets in Portfolio Balance
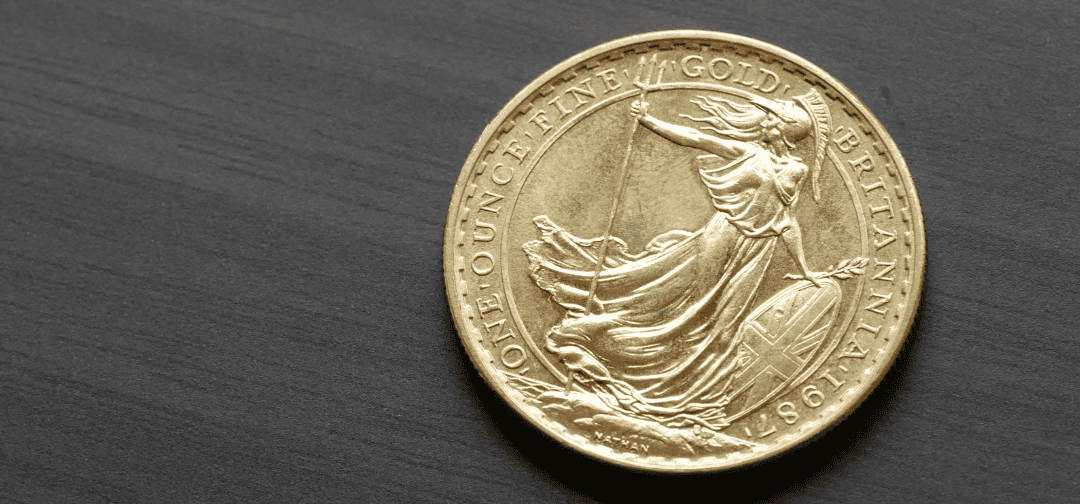
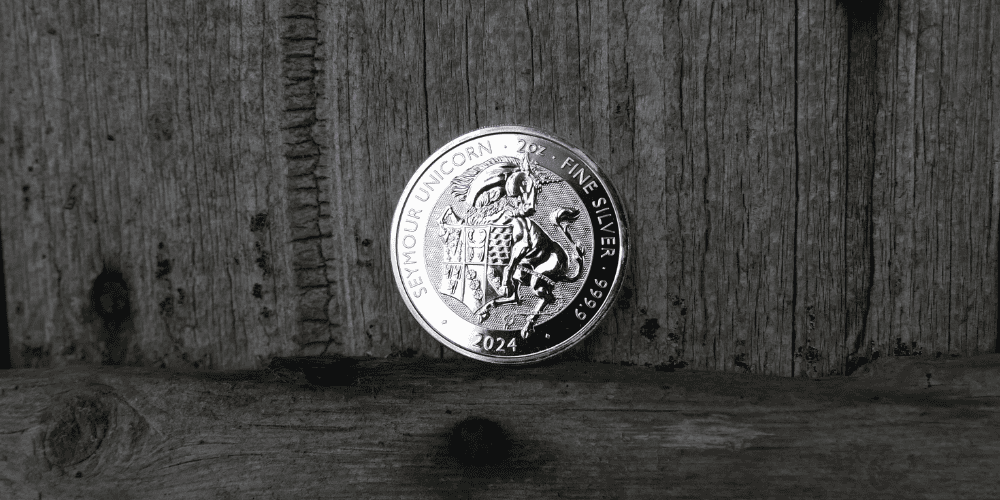
Throughout history, tangible assets such as gold and silver have been used as stores of value.
Their appeal often relates to their physical nature and global recognition.
Unlike digital financial instruments, physical precious metals exist independently of banking infrastructure.
They do not rely on platforms, logins, or intermediaries for custody.
For this reason, some investors include physical assets within a diversified portfolio as a way of balancing digital exposure.
Gold and silver have historically been valued for their durability, portability, and long-standing role within monetary systems.
Their role today is typically considered complementary rather than alternative.
Read 'Why Every Investment Portfolio Needs Precious Metals'
Diversification Is Not the Same as Distrust
It is important to recognise that most savers are not rejecting banks.
Banks provide essential services and remain central to the functioning of modern economies.
Instead, this gradual shift reflects a broader awareness of diversification principles.
Few investors hold all wealth in a single company or asset class. Applying similar thinking to custody structures can be viewed as an extension of this logic.
Diversification does not require dramatic change. Often, it simply involves incremental adjustments over time.
A Quiet Evolution in Financial Behaviour
Financial behaviour evolves alongside economic conditions, technology, and personal priorities.
The growing interest in holding some assets outside the banking system appears to reflect a desire for balance rather than a prediction of disruption.
By spreading wealth across different asset classes and custody structures, savers aim to reduce reliance on any single system.
For many, this approach supports long-term confidence and flexibility.
Understanding how wealth is structured can be just as important as understanding what assets are owned.
In an increasingly digital financial environment, clarity around both can help investors make calm and considered decisions.
Read 'Gold vs. Banks: Financial Privacy with Gold Matters More Than Ever'
Here to Help
If you’re considering buying gold or silver and would like to speak with someone first, our team is always happy to help. Whether you’re making your first purchase or adding to an existing portfolio, we can talk through your options and answer any questions you may have.
Call our team on 01769 618618 or email [email protected] for friendly, straightforward guidance.