
As pension holders grow more concerned about market volatility, inflation, and digital financial risks, an increasing number are turning to tangible assets like physical gold. A Self-Invested Personal Pension (SIPP) that holds physical gold can be an effective way to protect and grow retirement savings while maintaining tax efficiency, control, and long-term value.
In this article, we break down how gold SIPP accounts work, what to consider before opening one, and how to decide if it’s the right choice for your retirement strategy.
What Is a Gold SIPP?
A SIPP is a type of UK pension scheme that allows individuals to take greater control over their retirement savings. Unlike traditional pensions managed entirely by providers, SIPPs are self-directed, giving you the freedom to choose what assets to invest in, including physical gold.
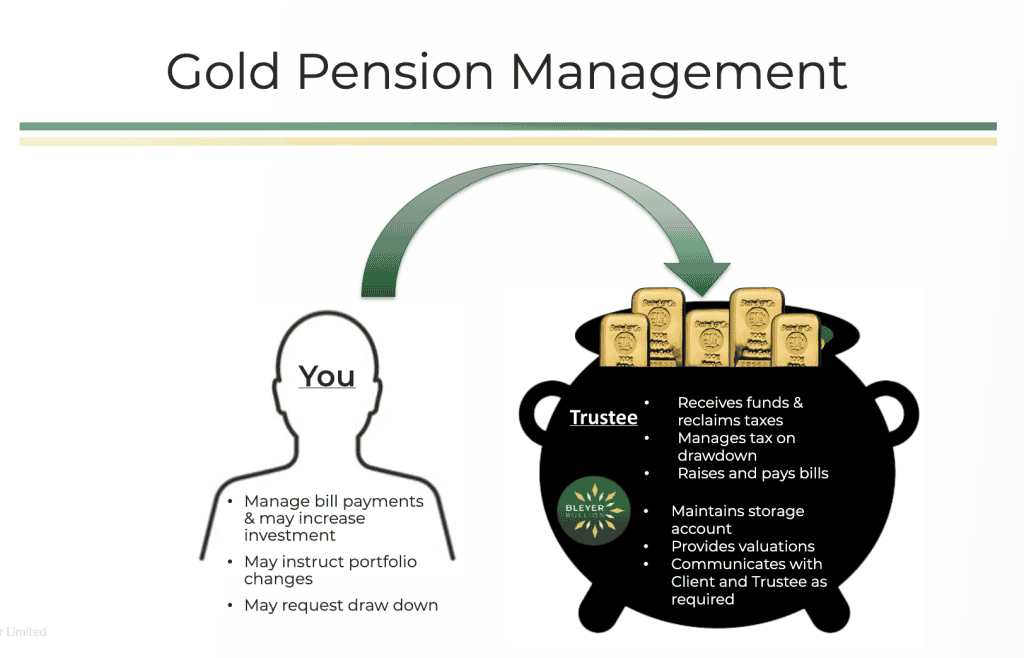
In a Gold SIPP, your pension funds are used to purchase real, allocated gold bars, which are securely stored in an approved vault. These gold holdings are managed in partnership with your chosen pension trustee and a reputable bullion dealer like Bleyer Bullion.
Benefits of Holding Gold in Your Pension
1. Tangible, Physical Asset: Gold is real, secure, and stored in your name. Many investors appreciate the peace of mind that comes from knowing exactly where their asset is held.
2. Tax Efficiency: Gold SIPPs qualify for the same tax relief as other pension investments. Contributions may benefit from tax relief at your marginal rate, and any gains made inside the pension are exempt from Capital Gains Tax (CGT).
3. Hedge Against Inflation and Economic Instability: Gold has historically preserved value during periods of high inflation, currency devaluation, and market downturns.
4. Portfolio Diversification: Because gold behaves differently from stocks or property, it provides balance in a mixed portfolio. SIPPs allow for this diversification, enabling you to combine gold with other HMRC-approved assets.
5. Legacy Planning: SIPPs can be passed on to beneficiaries and provide control over inheritance planning. Gold is particularly useful in preserving value across generations.
Read 'Building Your Future in Gold: Why Physical Gold Belongs in Your Pension'
How a Gold SIPP Works
Step 1: Choose a Pension Trustee
To set up a gold SIPP, you’ll need a trustee that supports physical bullion investments. Bleyer Bullion can recommend trusted providers or work with your chosen firm.
Step 2: Open and Fund the SIPP
After choosing a provider, you or your employer can contribute to your pension. Tax relief applies to contributions up to the annual limit (£60,000 as of 2025).
Step 3: Purchase the Gold
Once funds are available, you instruct your trustee to purchase gold through your dealer. In a SIPP, you can only purchase gold bars, not coins, which must meet HMRC standards.
Step 4: Secure Vault Storage
Your gold is securely stored in a high-security, fully insured vault, such as Bleyer’s partner facility. The gold remains in your name and fully allocated.
Step 5: Ongoing Management
You or your trustee will manage fees, receive regular valuations, and oversee the account. At retirement, you can begin to draw down income or a lump sum (25% tax-free, up to £275,000).
Costs to Consider for a Gold SIPP
Setting up a Gold SIPP involves a few key costs:
- SIPP setup fee (often reduced in special offers)
- Annual SIPP management fee
- Gold storage and vaulting fees
- Transactional fees (e.g., insertion/removal of gold)
It’s important to assess these in light of your investment amount and expected duration to ensure it remains cost-effective.
Can I Transfer an Existing Pension?
Yes. Many investors consolidate existing pensions into a gold SIPP. Pension trustees can assist in transferring stocks and shares pensions, provided the receiving SIPP supports gold investments.
Is Gold Right for Your Pension?
A gold SIPP may be right for you if:
- You value financial privacy and control
- You want to diversify away from paper-based or digital assets
- You are concerned about inflation, currency risk, or market instability
- You are looking for a long-term store of value for retirement
However, gold is not income-generating and may not suit those focused solely on yield. It is best used as part of a well-balanced portfolio.
Let Bleyer Help
At Bleyer Bullion, we help clients navigate gold pension investing with clarity and confidence. From selecting the right SIPP trustee to managing your gold storage, we offer tailored guidance every step of the way.
To learn more or book a free 1-to-1 consultation, contact us at 01769 618618 or email [email protected].