When planning for retirement, most of us want the same thing: confidence that the wealth we have built today will still be there when we need it.
Traditionally, pensions are invested across assets such as shares, funds and bonds. But for investors looking to diversify their retirement savings, physical gold can also form part of a retirement plan through certain Self-Invested Personal Pensions (SIPPs).
Gold has been used as a store of wealth for centuries. Rather than replacing traditional pension investments, physical gold can offer another way to diversify, preserve wealth and hold a tangible asset for the long term.
So, can you hold physical gold in your pension, how does a Gold SIPP work, and could it have a place in your retirement plan?
Why Consider Physical Gold for Retirement Planning?
Retirement planning is naturally long term. Over several decades, your savings may experience changing interest rates, inflation, currency movements and periods of stock market volatility.
Diversification can help reduce reliance on any one type of investment.
Gold behaves differently from many traditional financial assets and has historically been used as a store of wealth, particularly during periods of economic uncertainty and inflation.
For retirement investors, therefore, the question does not necessarily need to be gold or traditional investments. Instead, it can be about understanding whether physical gold has a place alongside other assets within a diversified retirement strategy.
Read 'Diversifying Your Investment Portfolio with Precious Metals'
Can You Hold Physical Gold in a Pension?
Yes. Physical gold can be held within certain Self-Invested Personal Pensions (SIPPs), provided the gold and pension arrangement meet the relevant requirements.
A SIPP is a type of pension that gives you greater control over how your retirement savings are invested. Some SIPP providers allow pension funds to be used to purchase qualifying investment-grade physical gold.
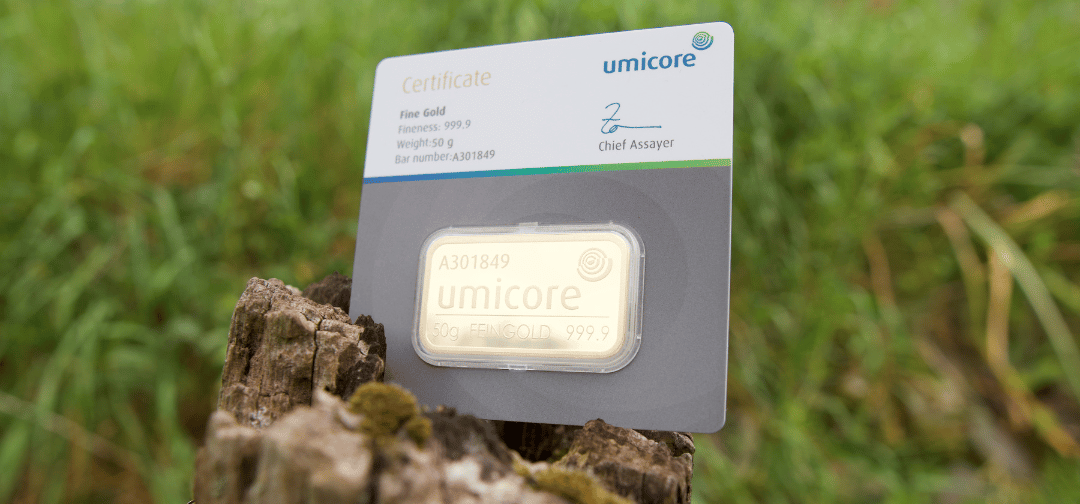
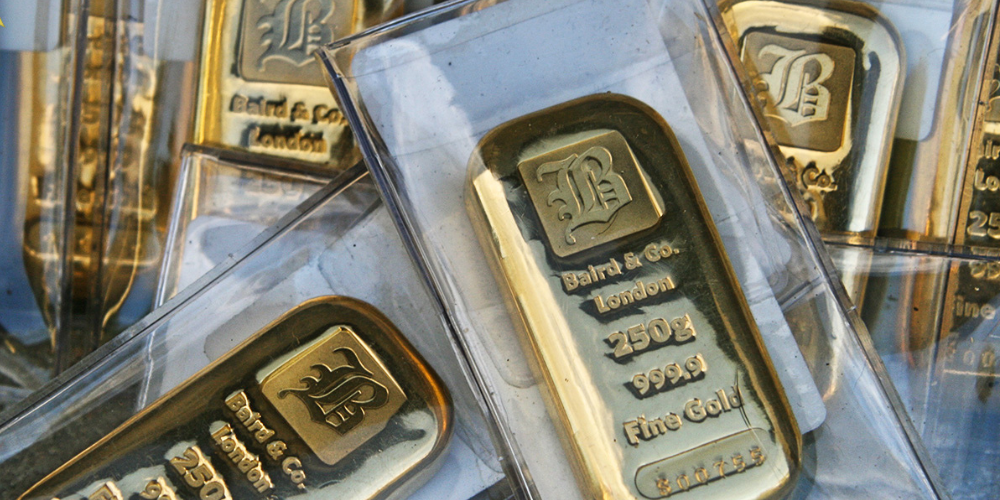
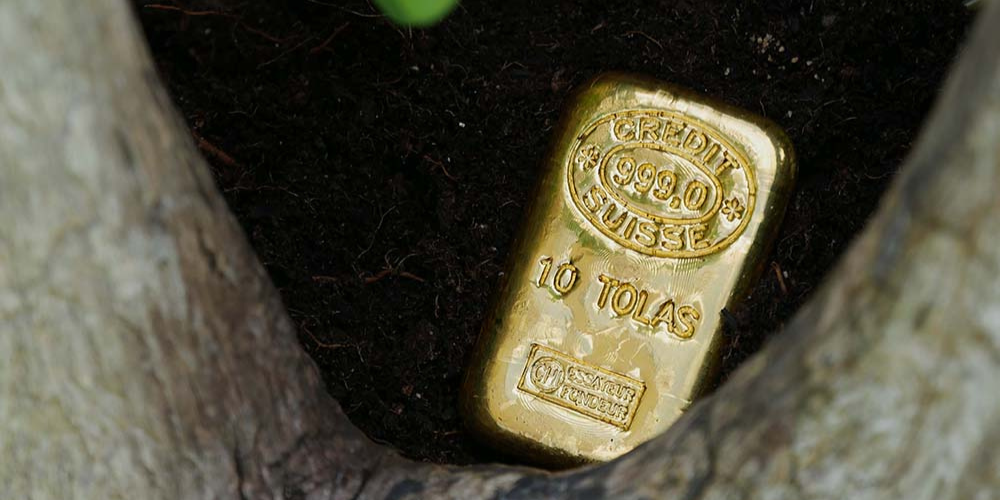
There is an important distinction here: physical gold held within a Gold SIPP must be in the form of qualifying gold bars. Bullion coins cannot be held within a SIPP in the same way.
The gold is purchased using pension funds and securely stored in an approved vault rather than being held personally at home.
Learn More About Gold Pensions
How Does a Gold SIPP Work?
A Gold SIPP might sound complicated at first, but the process can be relatively straightforward.
1. Choose a SIPP Provider
The first step is finding a pension provider that supports physical gold, as not every SIPP provider offers this investment option.
At Bleyer, we can work alongside your chosen pension provider or introduce you to providers experienced in facilitating physical gold SIPP investments.
2. Fund Your Gold SIPP
Once the SIPP has been established, it can be funded through pension contributions or, where appropriate, by transferring an existing pension.
Depending on your individual circumstances, eligible pension contributions may benefit from pension tax relief.
3. Purchase Qualifying Physical Gold Bars
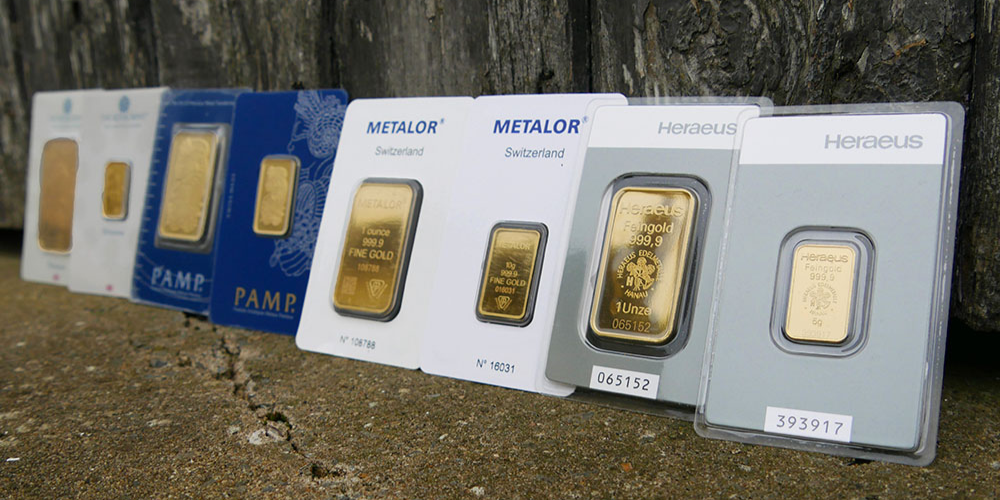
Funds held within the SIPP can then be used to purchase qualifying investment-grade gold bars that meet HMRC requirements.
Unlike gaining exposure to gold through a fund or other financial product, a Gold SIPP allows the pension to own real, allocated physical gold.
4. Securely Store Your Gold
Gold held within a SIPP must be professionally stored rather than kept at home.
The physical gold is held in secure, insured vaulting facilities and remains allocated to the pension.
5. Manage Gold Alongside Your Other Pension Investments
Physical gold does not have to make up your entire pension.
A SIPP can contain a range of permitted investments, allowing physical gold to sit alongside other assets as part of a wider retirement strategy.
Read 'How Do Gold SIPP Accounts Work and How to Decide If It Works for You'
What Are the Benefits of Physical Gold in a Retirement Plan?
There are several reasons investors consider physical gold for retirement planning.
Long-Term Wealth Preservation
Gold has been valued for thousands of years and has a long history as a store of wealth.
For retirement investors with a long time horizon, physical gold can provide an alternative way of holding wealth outside traditional financial assets.
Portfolio Diversification
One of the main reasons investors consider gold is diversification.
Gold can behave differently from shares and other investments, meaning an allocation to physical gold may help spread risk across different asset classes.
Rather than relying on one type of investment, a diversified retirement portfolio can combine assets with different characteristics.
A Tangible Asset
Physical gold is exactly that… physical.
For some investors, there is reassurance in knowing that part of their retirement savings is invested in real, allocated gold rather than relying entirely on financial or digital assets.
Pension Tax Efficiency
Physical gold held within a qualifying SIPP benefits from the tax treatment available within the pension wrapper.
Eligible contributions may receive pension tax relief, while gains made on investments held within the pension are not subject to Capital Gains Tax.
Global Recognition
Gold has an established international market and is recognised around the world.
This global recognition and liquidity are among the reasons gold has remained an important store of wealth across generations.
Does Physical Gold Replace Traditional Pension Investments?
Not necessarily, and this is an important distinction.
Gold does not generate an income in the way that some shares, bonds or property investments can. Its price can also rise and fall, and there are costs associated with buying, securely storing and administering physical gold within a pension.
For many investors, therefore, physical gold is about diversification rather than replacement.
A Gold SIPP can allow you to combine physical gold with other permitted pension investments, giving you greater flexibility over how your retirement savings are structured.
The right balance will depend on your circumstances, retirement goals and attitude towards investment risk.
Can You Transfer an Existing Pension Into a Gold SIPP?
For some investors, yes.
Existing pension funds may be transferable into a SIPP that supports physical gold, depending on the type of pension you currently hold and its terms.
You do not necessarily have to invest the entire transferred amount into gold. Physical gold can form one part of the SIPP alongside other permitted investments.
Before transferring an existing pension, it is important to understand your current arrangement and whether transferring could mean giving up valuable guarantees, benefits or protections.
Read 'Investing £50,000 into a Gold SIPP Pension: A Bleyer Success Story'
Is Physical Gold Right for Your Retirement Plan?
There is no single retirement strategy that suits everybody.
A Gold SIPP may be worth considering if you are looking to diversify your pension, value physical ownership and want to include a tangible store of wealth within your long-term retirement planning.
However, physical gold has its own risks and costs and does not produce an income. It should therefore be considered within the context of your wider pension and financial circumstances.
For many investors, the value of physical gold is not about trying to predict what its price will do next. It is about building a diversified retirement strategy designed to preserve wealth over decades, rather than reacting to short-term market movements.
Can Physical Gold Form Part of Your Retirement Plan?
Yes, qualifying physical gold can form part of a UK retirement plan through certain Self-Invested Personal Pensions.
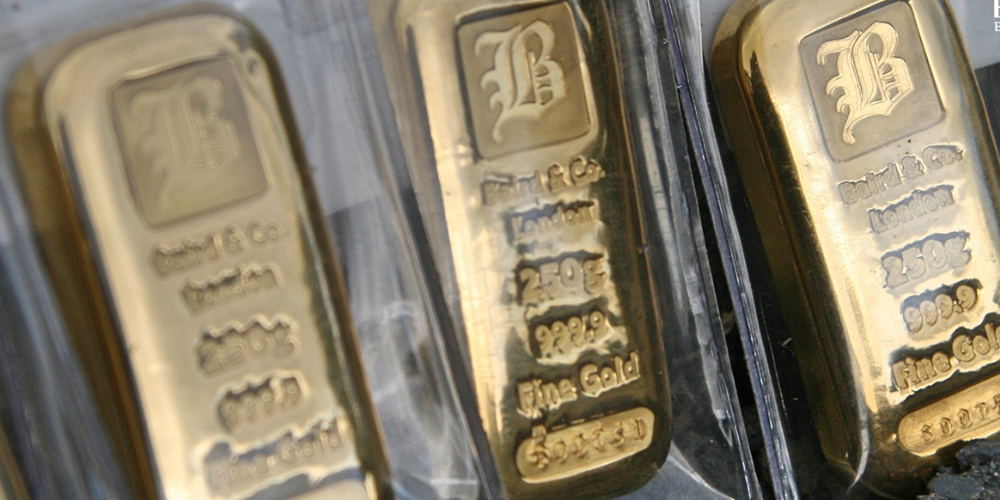
A Gold SIPP provides a way to hold real, allocated investment-grade gold bars within a pension wrapper, while retaining the flexibility to hold other permitted investments alongside them.
For investors thinking about the decades ahead, physical gold can provide another layer of diversification and long-term wealth preservation within a broader retirement strategy.
The important part is understanding how it works, the costs involved and how gold fits alongside your other retirement investments before making a decision.
Here To Help
At Bleyer, we believe retirement planning should start with understanding your options.
If you’re considering whether physical gold could form part of your retirement plan, our team can explain how Gold SIPPs work, introduce you to an appropriate pension provider and help with the purchase and secure storage of qualifying physical gold.
We always recommend considering your wider financial circumstances and seeking regulated financial or pension advice where appropriate before making changes to your pension.
Call the Bleyer team on 01769 618618 or email [email protected] for a friendly, no-obligation conversation.